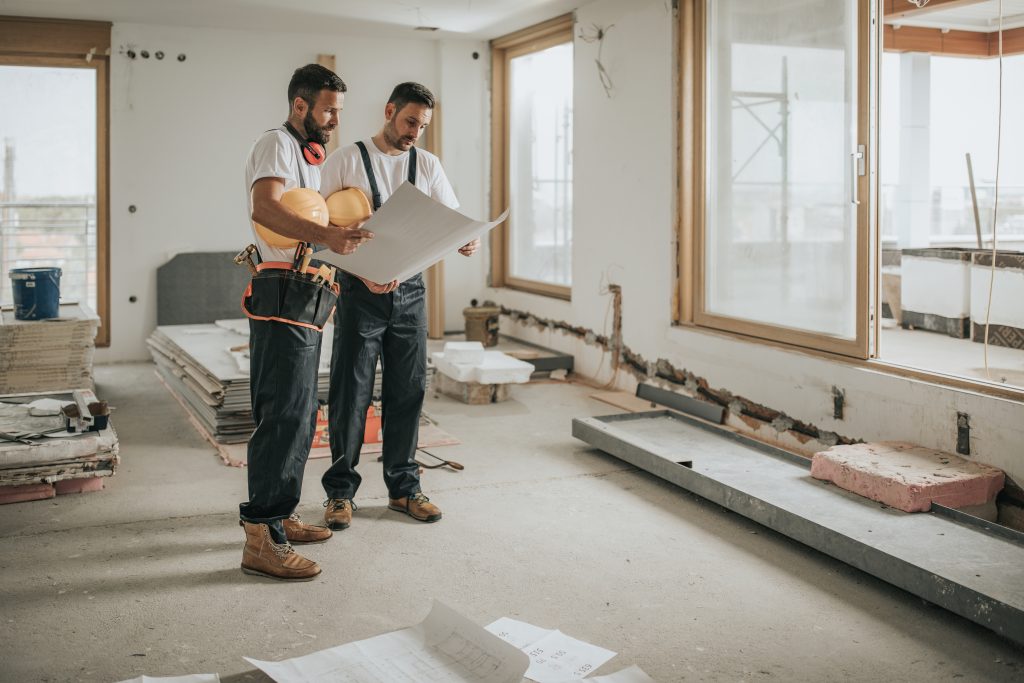
Buying your dream home and building are two different things. This is where construction loans come into the equation. A construction loan enables borrowers to finance the construction of their own home rather than purchase an established property
Construction loans in Australia are typically structured with a variable interest rate, per the Australian Securities and Investments Commission (ASIC) guidelines. It’s worth noting that not all lenders in Australia offer construction loans, as they are a more specialised type of loan.
What are Construction Loans?
Construction loans are home loans designed for borrowers building a new home or undertaking substantial renovations. These loans differ from traditional home loans as they provide ongoing payments to the builder as construction progresses, rather than a single lump sum payment.
With a construction loan, borrowers can draw on the loan balance when payments need to be made to the builder at critical stages of the building process. These progress payments allow borrowers to manage their cash flow during construction.
How do Construction Loans Work?
During the construction phase, borrowers are only required to make interest repayments on the amount of money drawn down rather than the entire loan amount. The lender then releases funds to cover the cost of the work completed. Interest is calculated on the outstanding loan balance, which increases as the borrower draws down more funds. This means that repayments are smaller at the start of the loan and increase gradually as the construction project approaches completion.
Construction loans typically have a variable interest rate and a maximum Loan to Value Ratio of 95%. However, the maximum LVR and interest rates can vary depending on the lender, so it’s essential to speak to a mortgage broker to understand the terms and conditions of different construction loans.
It’s also worth noting that lenders may set a maximum timeframe for the complete drawdown of the loan, usually around six months.
Progressive Payments: The Lowdown
Once a borrower is approved for a construction home loan and building work commences, lenders will provide progressive payments throughout the various stages of construction. These payments are typically made directly to the builder after completing each build step.
The progressive payments are generally structured into the following stages:
Slab down or base stage
This payment is for laying the foundation of the build. It includes measuring the site, excavating foundations, pouring the footings, under slab drainage, and moisture barrier protection.
Frame stage
This payment is for raising the frames of the house. This stage can include erecting external and internal support structures, trusses, and running conduits for electrical and plumbing services.
Lockup stage
This payment is intended to secure the property, including finishing the external walls and installing windows and doors. After this stage, the house should be able to be locked, and it should be safe for the internal tradespeople to enter the house and begin the interior fit-out.
Fit-out or fixing stage
This payment is for completing the fit-out of the home, including all internal fittings and fixtures. This includes plumbing, electrical, plaster boarding, initial cabinet installation, tiling, and architraves.
Practical completion
This payment concludes all contracted items, such as finishing all carpentry, electrical, plumbing, painting, detailing, and cleaning. After this stage, the borrower should be able to move in and live in their new home.
Sometimes, a builder may request a deposit before any planning occurs. In such cases, borrowers may negotiate with their lender for advancement on their first progressive payment. It's recommended that borrowers have additional funds on standby to keep the construction process moving forward.

Buying a Fixer-Upper Home. Is it For You?
Purchasing a property is undeniably one of life’s significant milestones. However, when buying a “fixer-upper” home, a whole new level of complexity is added to
Aussie Home Loans vs the Market: Are You Getting the Best Rate?
Finding the right home loan in Australia can feel like navigating a maze with no clear exit. With dozens of lenders competing for your business
Can an Australian Expat Get a Construction Loan?
As an Australian expat living overseas, the prospect of building your dream home back in Australia can be both exciting and challenging. One critical

The Borrowers Guide To Lending
The purpose of this Borrowers Guide to Lending is to provide you with a clearer comprehension of the lending procedure. The mortgage application process can
RBA Interest Rate Announcement Today: Cash Rate Rises to 4.35% in May 2026
Reserve Bank of Australia lifts cash rate as inflation pressures intensify In a closely watched RBA interest rate decision today, the Reserve
Partial Offset vs 100% Offset: What’s the Difference?
Offset Accounts Explained: How They Work and Save You Money One feature that can make a home loan more attractive is the option to link