Buying an investment property can feel exciting at first. You picture rental income, long-term wealth, and financial freedom. Then the invoices start arriving. Suddenly, your investment home loan comes with application fees, lender charges, stamp duty, property management costs, insurance, council rates, and surprise repairs you never saw coming. That’s why understanding every investment mortgage fee before you apply is critical.
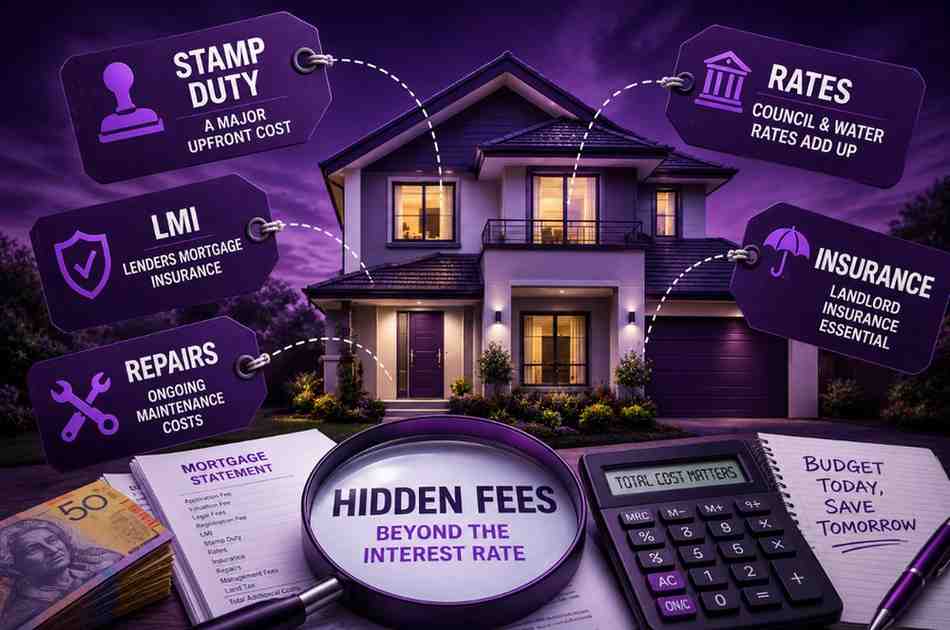
Whether you’re comparing investment home loan rates from Bendigo, Westpac, ANZ Mystate bank, or specialist lenders, knowing the true cost of an investment mortgage can save you thousands. In this guide, we break down every major investment home loan fee in simple terms, explain what most investors overlook, and show you how to compare the real cost of a house loan — not just the advertised interest rate.
What Fees Are Involved in an Investment Home Loan?
Investment house loan fees usually fall into three categories:
- 1-Upfront property purchase costs
- 2-Ongoing mortgage and property expenses
- 3-Exit and refinancing costs
Some fees are unavoidable. Others can be reduced, negotiated, or avoided completely. The key is understanding what lenders charge and how those costs affect your cash flow and investment returns.
Mortgage Upfront Fees
1.1- Application or Establishment Fee
One of the first investment mortgage fees you may encounter is the application or establishment fee. This is charged by the lender for processing your home loan application. Depending on the lender, this fee may include:
- -Credit assessment
- -Loan setup
- -Documentation processing
- -Administrative costs
Some lenders charge several hundred dollars, while others offer no application fee promotions. When comparing investment home loans, always check whether the lender has hidden setup costs buried in the fine print.
2.2- Valuation Fee for an Investment Property Loan
Before approving an investment home loan, lenders normally order a professional property valuation. This helps the bank determine the market value of the property and confirm the level of risk involved in the mortgage. Valuation fees vary depending on the location, property type, and loan complexity. Some lenders absorb this cost, while others pass the fee directly onto borrowers.
Why Do Investment Home Loan Fees Matter So Much?
Many investors focus only on the interest rate. That’s a mistake. A low-rate investment mortgage with high fees can sometimes cost more than a slightly higher-rate home loan with fewer charges. That’s why comparing the comparison rate is essential. According to Moneysmart, the comparison rate includes the interest rate plus many standard fees and charges, giving borrowers a clearer picture of the total loan cost.
3.3- Legal and Conveyancing Fees
Every property purchase involves legal work. Conveyancers and property solicitors manage the title transfer, contract reviews, settlement process, and legal documentation required for the purchase. These fees vary depending on the complexity of the transaction and the state in which the property is located. While it may be tempting to choose the cheapest option available, experienced investors know that quality legal support can prevent expensive problems later.
4. 4-Stamp Duty on Investment Property Purchases
Stamp duty is often the largest upfront cost involved in purchasing an investment property. This government tax applies when buying real estate in Australia, and the amount depends on the property’s value, location, and buyer status. Investment property buyers usually pay more than owner-occupiers because they often miss out on first-home buyer concessions and discounts. Many investors are shocked by how quickly stamp duty increases as property prices rise. You can estimate these costs using calculators from your state revenue office or lenders such as Macquarie Bank
5. 5-Mortgage Registration Fees
This government fee covers the cost of registering the mortgage against the property title. It’s relatively small compared to stamp duty but still important to budget for. Each Australian state and territory charges different registration fees.
6.6- Lenders Mortgage Insurance (LMI)
Lenders Mortgage Insurance is one of the most misunderstood investment home loan costs. LMI usually applies when the borrower has less than a 20% deposit. Many people mistakenly believe this insurance protects them, but it actually protects the lender if the borrower defaults on the mortgage. For investment properties, LMI premiums can become extremely expensive depending on the loan amount, deposit size, and risk profile. In some cases, the premium can add tens of thousands of dollars to the total loan cost.
What Is the Most Expensive Investment Home Loan Fee?
For many investors, the largest costs include stamp duty, mortgage interest, Lenders Mortgage Insurance, and ongoing maintenance expenses. These are the hidden costs that often surprise first-time investors who expected the rental income to cover everything comfortably.
Ongoing Investment house loan fees
7.7- Building and Pest Inspection Fees
Before purchasing an investment property, building and pest inspections are strongly recommended. These inspections can uncover hidden structural issues, termite damage, water leaks, electrical problems, or major repair risks.
Skipping inspections may save money upfront, but it can create massive financial stress later if expensive defects are discovered after settlement.
8.8- Annual or Monthly Package Fees
Many lenders charge annual package fees or monthly account maintenance fees on investment mortgages. These fees may include features such as offset accounts, interest rate discounts, credit cards, or bundled banking products. Sometimes these packages provide strong value. Other times they simply increase the total cost of the home loan without offering meaningful benefits.
9. 9-Interest Costs on an Investment Mortgage
Interest is the largest long-term cost of an investment home loan. Investment loan rates are often slightly higher than owner-occupier rates because lenders consider them higher risk. Investors may choose Principal and interest repayments or Interest-only repayments. Interest-only investment loans can improve short-term cash flow, but they may cost more over time due to higher interest rates and slower debt reduction.
Should You Choose Interest-Only Investment Loans?
Interest-only home loans can help investors maximise cash flow and potentially increase tax deductions. But there is a downside many borrowers overlook. Once the interest-only period ends, repayments can rise dramatically. That sudden jump catches many investors by surprise and can place pressure on household finances.
10.10- Property Management Fees
If you hire a real estate agent to manage your investment property, you will pay ongoing property management fees. These fees generally cover tenant communication, rent collection, inspections, maintenance coordination, and lease management. Most property managers charge a percentage of the weekly rental income. For many investors, the convenience is worth the cost, especially when managing properties from interstate or balancing busy work schedules.
11. 11-Body Corporate or Strata Fees
Investors purchasing apartments, units, or townhouses may also face body corporate or strata levies. These fees contribute toward maintaining common areas such as lifts, pools, gardens, building insurance, and shared facilities. Some apartment complexes have surprisingly high strata costs, which is why reviewing strata records before purchasing is essential.
12. 12-Landlord Insurance Costs
Landlord insurance protects investment property owners from risks such as tenant damage, rental loss, theft, storms, and legal liability. Many experienced investors consider landlord insurance essential because unexpected tenant problems can quickly become expensive.
13. 13-Council Rates, Water Rates, and Utilities
Investment property owners are responsible for ongoing property-related expenses including council rates, water rates, sewage charges, and certain utility costs. These expenses vary significantly depending on the property location and local council area.
14. 14-Land Tax on Investment Properties
Most Australian states charge annual land tax on investment properties. Land tax thresholds and rates vary by state. This is an important cost many new investors forget to include in their budgeting calculations. You can check current rules through your state revenue office or ATO guidance for property investors.
15. 15-Maintenance and Repair Costs
Every investment property eventually needs repairs. Even newer homes can experience plumbing problems, electrical faults, appliance failures, or emergency maintenance issues. Older properties can become especially expensive if major systems such as roofing, hot water services, or drainage need replacing. Smart investors usually maintain a financial buffer for unexpected repair costs. Experienced investors often keep an emergency repair fund ready.
16.16- Advertising Fees for Finding New Tenants
When tenants move out, landlords may need to pay advertising costs to find new renters. Vacancy periods can also reduce rental income. This becomes especially stressful during slower rental markets.
17.17- Renovation and Improvement Costs
Many property investors renovate to increase rental returns or improve the property’s market value. Some renovations are simple cosmetic improvements such as repainting walls or replacing flooring. Others involve larger projects like bathroom upgrades or kitchen renovations. While renovations can improve rental appeal, they can also become expensive quickly if budgets blow out.
18.18- Redraw Fees and Early Repayment Fees
Some investment mortgages include fees for redraw facilities, additional repayments, or breaking a fixed-rate loan early. These charges are often hidden deep within loan documents, which is why reading the fine print carefully matters. A mortgage with a cheap headline rate may still become costly if restrictive fees limit flexibility later. cheap rate with restrictive fees may not suit flexible investors.
Exit fees House Loan
19. 19-Discharge Fees When Selling or Refinancing
When borrowers refinance or close their mortgage, lenders may charge discharge or settlement fees. These costs cover administration, title processing, and final loan closure procedures. Although relatively small compared to other investment property expenses, they still contribute to the total cost of refinancing.
How Can You Reduce Investment Home Loan Fees?
Here are a few practical ways investors reduce costs:
a-Compare Investment Home Loan Rates Carefully
Reducing investment home loan costs starts with comparing lenders carefully. Many borrowers only compare interest rates, but experienced investors also review package fees, offset account costs, comparison rates, redraw charges, and loan flexibility.
b- Negotiate With Lenders
Negotiating with lenders can also reduce costs, especially for borrowers with strong equity positions or multiple investment properties.
c- Use Mortgage Calculators Before Applying
Using mortgage calculators before applying can help estimate repayments, borrowing power, stamp duty, and long-term interest costs before committing to a property purchase.
Frequently Asked Questions About Investment Home Loan Fees
What costs are involved in an investment house loan?
Investment home loan fees usually include application fees, valuation fees, legal costs, stamp duty, mortgage registration fees, Lenders Mortgage Insurance, ongoing bank fees, property management fees, council rates, insurance, maintenance costs, and discharge fees.
Are investment home loan rates higher than owner-occupier loans?
Yes. Investment mortgage rates are often slightly higher because lenders view investment lending as higher risk.
What is the comparison rate on an investment mortgage?
The comparison rate combines the interest rate and many standard loan fees to help borrowers compare the true cost of different home loans.
Can you avoid Lenders Mortgage Insurance on an investment property?
Yes. Most borrowers avoid LMI by providing at least a 20% deposit.
Are investment property fees tax deductible?
Many investment property expenses may be tax deductible, including loan interest, management fees, insurance, and repairs. Always seek advice from a qualified tax professional.
Final Thoughts
An investment property can become a powerful long-term wealth-building strategy, but the hidden costs can easily catch borrowers off guard. I have seen many investors focus entirely on the advertised mortgage rate while ignoring the true cost of owning the property. The smartest investors compare everything, including interest rates, lender fees, government charges, ongoing maintenance expenses, and long-term cash flow impacts. Understanding the full cost of an investment home loan before you buy can help you avoid financial stress later and make more confident investment decisions.
Ready to compare investment house loan rates?
Visit Ratebuster to compare house loan rates today, explore mortgage calculators, and find competitive investment mortgage options that could save you thousands over the life of your loan.