Can You Use an SMSF for Green Property Investments?
Yes — you can use a Self-Managed Superannuation Fund (SMSF) to invest in green or sustainable property, provided the investment meets Australian superannuation laws and your SMSF’s investment strategy allows it.
Super law places no restriction on SMSFs investing in environmentally sustainable property. What matters is not whether the property carries a “green” label, but whether the investment:
- Is made solely to provide retirement benefits
- Is acquired and managed on arm’s-length, commercial terms
- Fits within the fund’s documented investment strategy
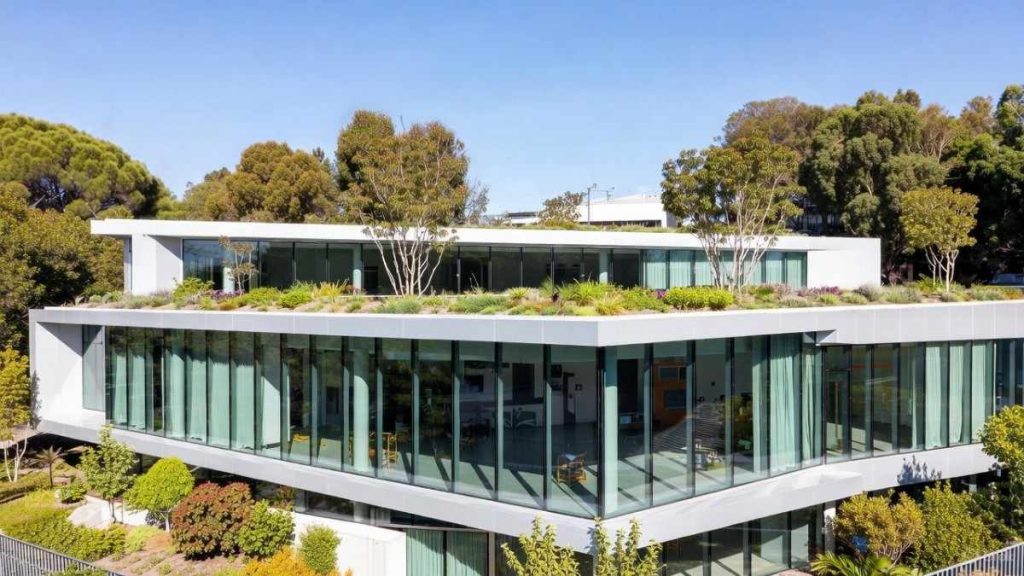
This means SMSFs can invest in properties with features such as energy efficiency, solar power, water-saving systems, or recognised sustainability ratings like NABERS or Green Star — as long as the investment meets all compliance rules.
What Is a Green or Sustainable Property Investment?
Sustainable property investing goes beyond a buzzword. It represents a long-term strategy that focuses on environmental performance, social responsibility, and strong governance (ESG principles).
Common features of green property investments include:
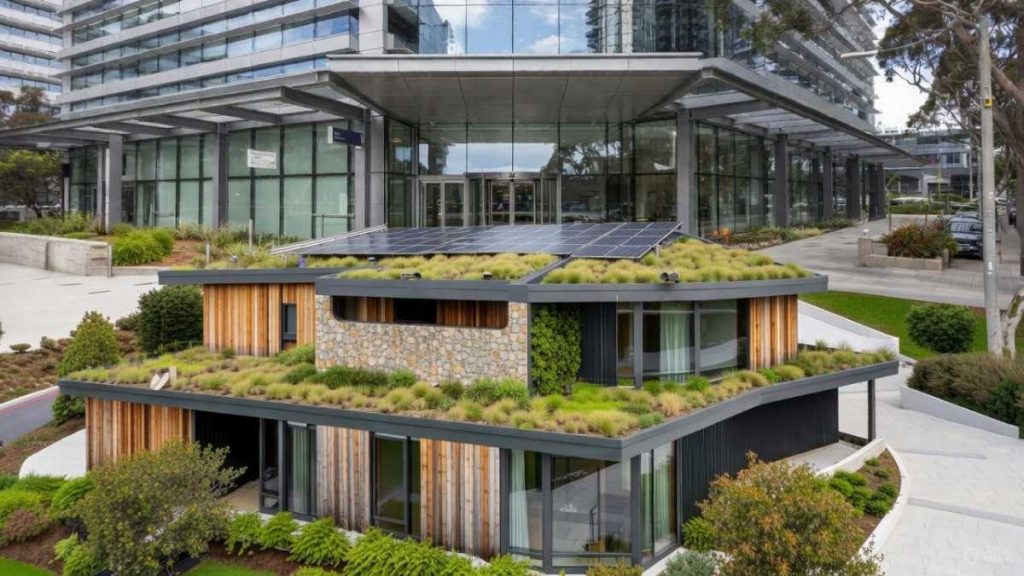
- Energy-efficient design and renewable energy (solar panels, insulation, double glazing)
- Water conservation systems
- Sustainable building materials
- Waste reduction and recycling initiatives
- Ethical property management and tenant wellbeing
In Australia, demand for sustainable buildings continues to grow rapidly, particularly in the commercial property sector, where tenants increasingly value lower operating costs and strong environmental credentials.
Why Sustainable Property Can Work Well Inside an SMSF
- Long-Term Returns and Retirement Focus
SMSFs are designed for long-term investing — which aligns well with sustainable property. Green buildings often:
- Attract higher-quality, longer-term tenants
- Have lower running costs
- Hold value better over time
- Face less risk from future regulatory changes
These factors support the sole purpose test, as they help trustees build stable retirement outcomes rather than short-term gains.
2.Higher Property Valuations
Green homes and buildings often achieve higher valuations due to lower energy costs and improved comfort. For SMSFs that use borrowing (via an LRBA), this can:
- Improve loan-to-value ratios (LVRs)
- Potentially reduce interest costs
- Improve overall investment viability
Residential vs Commercial Green Property in an SMSF
Commercial Green Property
It is often the preferred option for SMSF investors, especially when sustainability is involved.
Benefits include:
- Ability to lease to a related business (on market terms)
- Longer lease periods
- Tenants willing to pay a premium for energy-efficient buildings
- Easier compliance compared to residential property
Residential Green Property
SMSFs can also invest in residential green property, but strict rules apply:
- Members or related parties cannot live in or use the property
- No personal benefit is allowed — even at market rent
- The investment must be purely for retirement purposes
Because of these limits, residential green property is usually better suited to SMSFs with strong compliance support and a clear long-term strategy.
SMSF Rules You Must Still Follow
Even when investing in sustainable property, standard SMSF property rules apply.
- Sole Purpose Test
The investment must exist only to provide retirement benefits. Trustees cannot allow personal use, lifestyle benefits, or preferential treatment.
- Arm’s-Length Transactions
The purchase price, rent, and expenses must reflect true market value, especially when a related party is involved.
- Investment Strategy Requirements
Your SMSF must document:
- Why green property suits your fund
- Risk and return expectations
- Diversification considerations
- Liquidity and cash-flow planning
Sustainability goals can be included — but they must support financial outcomes.
- Borrowing Rules (LRBA)
If the fund uses borrowing:
- The loan must be limited recourse
- The property must be held in a bare trust
- Renovations and improvements are restricted
Government Incentives and Regulatory Support for Sustainable Property Development
Australia is at the forefront of sustainable property regulation. Governments actively encourage green building through:
- Energy efficiency standards
- Emissions reduction policies
- Grants, rebates, and tax incentives (where applicable)
For SMSF investors, this support reduces regulatory risk and strengthens long-term value. Investing ahead of sustainability requirements can position your fund favourably as standards tighten over time.
Is Green Property Through an SMSF Worth It?
For the right investor, yes — it can be worth it.
Green property investments through an SMSF may suit you if:
- You have a long-term retirement focus
- You want stable income and resilient asset values
- You prefer commercial or specialist property
- Your fund has sufficient balance and liquidity
- You are comfortable with SMSF compliance obligations
However, SMSF property investing is complex. Professional advice remains essential to ensure the structure, lending, and investment strategy meet all compliance requirements.
Learn how to look up smsf here