If you’re considering refinancing, understanding the difference between investment property loans and owner-occupied home loans is crucial. While both involve borrowing against property, the rules, rates, and tax implications can vary dramatically.
In today’s changing market — with fluctuating interest rates and tighter lending conditions — the decision to refinance should be guided by more than just securing a better rate. Let’s explore what changes when you refinance an investment property compared to your own home, and how lenders assess each type differently.
Understanding the Difference Between Investment and Owner-Occupied Loans
At the most basic level, owner-occupied home loans are for properties you live in, while investment property loans are used to purchase or refinance a property that you rent out. However, when it comes to refinancing, lenders treat these categories differently due to their varying risk levels and potential returns.
Why Lenders Treat Investment Properties Differently
Investment loans are generally considered higher risk by lenders. Rental income can fluctuate, tenants can leave, and investors might be more leveraged than owner-occupiers. For this reason, interest rates on investment property loans tend to be slightly higher, and serviceability requirements can be stricter.
By contrast, owner-occupied loans often attract lower rates and fewer restrictions because borrowers have a personal stake in maintaining repayments — it’s their home. (APRA) – Lending Standards
What Changes When You Refinance an Investment Property
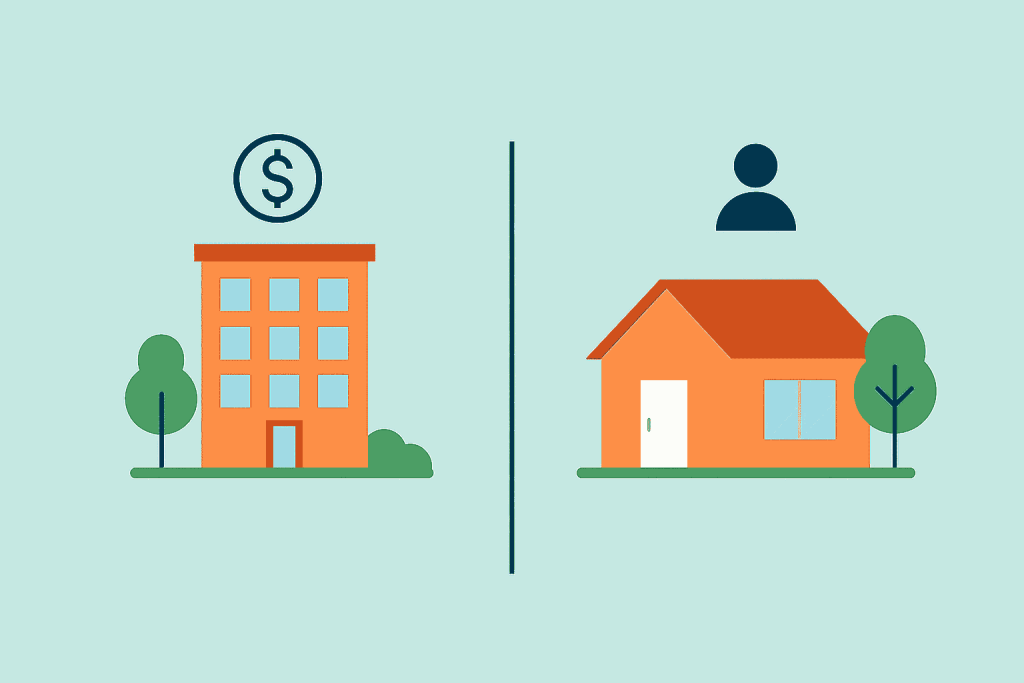
When you refinance your investment property, the goal might be to reduce repayments, release equity, or restructure your loan portfolio. However, the process and benefits can differ significantly from refinancing an owner-occupied property.
Interest Rates and Loan Terms
Lenders typically charge higher rates on investment property refinances than on owner-occupied loans. The gap can vary from 0.25% to 0.75%, depending on the lender’s risk appetite and market conditions.
Additionally, some banks limit interest-only terms to five years for investment loans, after which they revert to principal-and-interest. This structure is designed to encourage repayment discipline and reduce risk exposure.
Equity Access and Borrowing Power
Investors often refinance to unlock equity — using existing property value to fund renovations, new purchases, or other investments. However, lenders apply stricter loan-to-value ratio (LVR) limits on investment loans, often capping borrowing at 80% of the property’s value.
In contrast, owner-occupiers may access up to 90–95% LVR with mortgage insurance. The difference lies in how lenders assess risk and repayment capacity based on rental income versus personal earnings.
Tax Deductibility and Investment Benefits
One of the biggest distinctions is tax treatment. Interest on investment property loans may be tax-deductible, while interest on owner-occupied loans is not. Refinancing doesn’t change this rule — it depends on how the borrowed funds are used.
For example, if you refinance your investment property to renovate or purchase another income-generating asset, the interest remains deductible. However, if you use equity for personal spending (like a car or holiday), that portion of interest becomes non-deductible. (Australian Taxation Office (ATO)
How Lenders Assess Owner-Occupied Refinancing
When refinancing your owner-occupied home loan, the focus is often on securing a better rate, shorter term, or lower fees.
Credit and Income Assessment
Owner-occupiers are assessed primarily on their personal income, job stability, and expenses. Because lenders perceive less volatility in these income sources compared to rental income, owner-occupied refinances tend to be approved faster and with more favourable terms.
Borrowers who have built equity in their homes and maintained consistent repayment history may also qualify for rate discounts or cashback offers.
Purpose and Equity Use
Using equity from your home to fund renovations or pay off other debts is common. However, if you plan to use that equity for investment purposes, the lender might reclassify your loan as an investment product — which can affect rates and conditions.
It’s important to disclose the purpose of your refinance upfront to ensure the loan is structured correctly and remains compliant.
Refinancing Strategy — Investment vs Owner-Occupied
Now that we’ve covered the mechanics, how can borrowers create a refinancing strategy that maximises benefits while minimising risk?
Smart Strategies to Manage Your Super and Property Investments
Refinancing investment properties isn’t just about chasing lower rates — it’s about aligning your property and superannuation strategy for long-term wealth creation.
Some investors use refinancing to free up capital for Self-Managed Super Fund (SMSF) property purchases or to reduce debt exposure across multiple assets. The key is balancing leverage with sustainability.
If your goal is to grow your investment portfolio while maintaining strong cash flow, consult a licensed adviser to ensure your refinancing structure supports both your super and property goals in a compliant, tax-efficient way.
When to Refinance an Investment Property or Home Loan
Timing can be everything in refinancing. Market trends, interest rate cycles, and personal financial circumstances all influence when to act.
Market Conditions and Rate Movements
If interest rates have fallen since you took out your original loan, refinancing could deliver immediate savings. Likewise, if property values in your area have risen, you may have more equity to leverage for better terms.
However, refinancing too frequently can lead to exit fees, break costs, or lost benefits, especially for fixed-rate borrowers. Always weigh potential savings against total switching costs before proceeding.
Key Considerations Before Refinancing
Before refinancing, ask yourself the following questions:
-
Are you switching to reduce repayments or access equity?
-
Do you plan to use borrowed funds for investment or personal use?
-
Is your current lender offering a competitive rate?
-
Have your financial circumstances changed since your last loan review?
Being clear on your goals helps ensure you select the right loan type — and that you stay compliant with lender policies and tax rules.

The Bottom Line — Refinancing with Purpose
Refinancing can be a powerful tool whether you’re upgrading your home, expanding your investment portfolio, or simply trying to improve cash flow.
While owner-occupied loans often come with lower rates and simpler conditions, investment property refinances offer opportunities for leverage and wealth growth — albeit with higher risk and complexity.
The key lies in matching your refinance to your financial goals and risk profile.
Before refinancing, compare offers from multiple lenders to ensure you’re getting the best deal.
Visit RateBuster.com.au to explore competitive home loan rates, refinancing options, and expert insights to help you make confident, informed decisions.
Helpful content: