Negative Equity in Your Mortgage: What You Need to Know

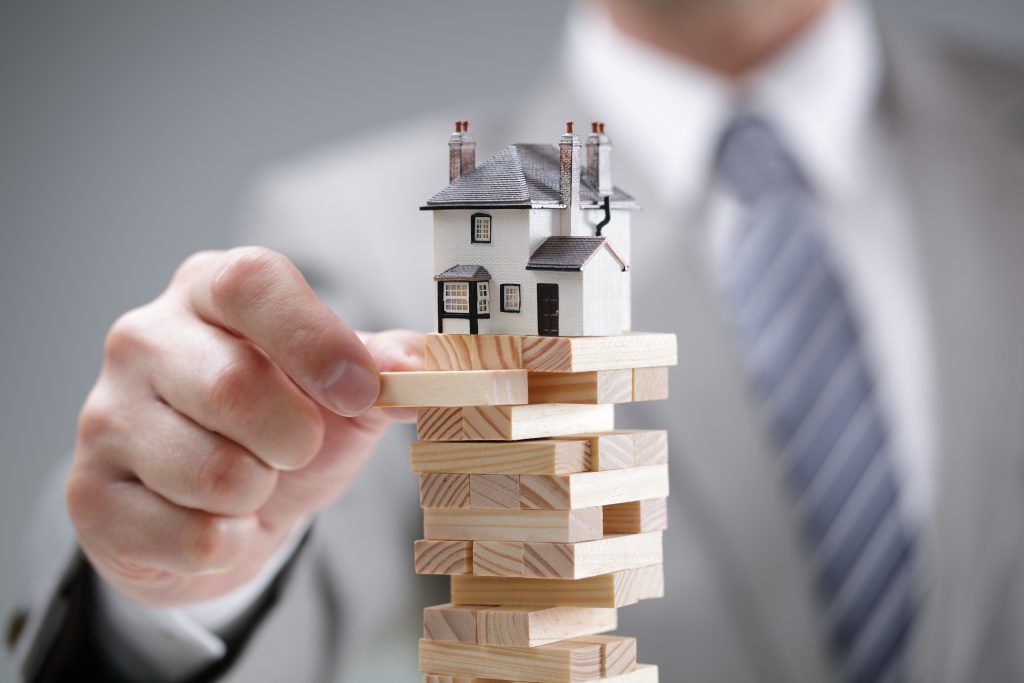
Negative equity occurs when a loan’s outstanding balance is more significant than an asset’s value, such as a property. In the context of homeownership, negative equity can happen when the value of a property drops below the amount owed on the mortgage. This means that if the property were to be sold, the proceeds would not be enough to cover the outstanding mortgage balance, leaving the homeowner with a deficit.

Negative Equity Explained

Negative equity occurs when the outstanding balance on a loan is more than the value of an asset. This can happen in various ways, such as buying an investment when market prices are high and then seeing a decline in local prices, putting a down payment on an asset and then experiencing a decrease in its value, or missing payments early on in the loan term and accumulating interest. 


For instance, if you purchase a home worth $150,000 with a 10% down payment of $15,000 and take on a mortgage of $135,000, you have $15,000 in equity. However, if a year later, your home’s value drops to $120,000, and you have only paid off $1,000 of the loan principal, you still owe your lender $134,000. This situation leaves you with $14,000 in negative equity. 


Negative equity can pose problems for homeowners, challenging refinancing or selling their assets. Lenders cannot loan more money than the property is worth, making it impossible to refinance more than the asset’s current value. Additionally, if a homeowner sells their asset and there is still an outstanding balance, they must cover it before the lender closes the loan. 

Preventing Negative Equity

Consider Current Market Prices  

The first step to avoiding negative equity is to be mindful of the current market conditions. Before you purchase a home, take some time to research the housing market in your area. If the market is strong and property values rise, you’ll likely build equity over time. Talk to a real estate professional to better understand what to expect. 

Put More Money Down  

While buying a home with a small down payment is possible, doing so can be risky. If your local housing market takes an adverse turn, you could quickly find yourself in negative equity. To avoid this situation, aim to save a larger down payment or consider buying a more affordable property. Putting more money down upfront can also reduce your monthly mortgage payments, making it easier to keep up with your bills. 

Don’t Buy More Home Than You Can Afford 

It’s essential to be realistic about what you can afford when purchasing a home. Taking on a mortgage beyond your means can quickly lead to financial trouble. If you struggle to make your payments early on, you’ll begin to build negative equity.  Before you sign on the dotted line, ensure you’ve accounted for all the costs of owning a home, including property taxes, utilities, and maintenance. 

Keep Your Home Well-Maintained  

Finally, to protect your home’s value, keep it well-maintained. Regular maintenance and repairs can help prevent minor issues from becoming more significant problems that could affect your property’s value. Keeping your home in good condition can also make it more attractive to potential buyers if you decide to sell in the future. 

How Negative Equity Occurs

Buying at the Peak of the Market Cycle  

Purchasing a property when the market is at its highest point can cause negative equity. As the market contracts, the property’s value decreases, which may result in a loan amount that exceeds the property’s current value. 

Overpaying for the Property  

Emotional purchases or competitive bidding can lead to overpaying for a property, which puts the buyer at a disadvantage for potential capital growth. Overpaying for a property means the buyer has paid more than the property’s actual value, reducing equity. 

High Loan-to-Value Ratio  

Purchasing a property with a low deposit and high loan-to-value ratio can also cause negative equity. With a smaller deposit, the property has less equity, leaving the borrower vulnerable to market fluctuations. 

Overcapitalisation  

Overcapitalisation happens when a property’s renovation cost exceeds its value. For instance, if a borrower spends $100,000 on a renovation that only increases the property’s value by $50,000, they have overcapitalised. This can result in the property being worth less than the outstanding loan amount, leading to negative equity. 

Avoiding negative equity requires careful planning and research before purchasing a property. It is essential to assess market conditions, buy a property at its actual value, and have an appropriate loan-to-value ratio. Homeowners should also avoid overcapitalising and ensure that renovation costs are proportional to increased property value. 

alt

    Simply Enter Your Details To Speak To A Certified Mortgage Advisor About Your Loan Today.


    alt

    About