How much is lenders mortgage insurance is one of the most important questions any home buyer can ask before committing to a home loan. It’s a cost that can quietly add thousands to your mortgage, yet it can also be the key that unlocks property ownership years earlier than expected. Lenders Mortgage Insurance (LMI) sits at the centre of many first home buyer decisions, influencing deposit strategy, borrowing power, and long-term wealth outcomes. I’ve seen borrowers hesitate because of it, only to watch property prices climb out of reach, while others have used it strategically to secure a home sooner and build equity faster. Understanding exactly how LMI works, how much it costs, and when it makes sense to pay it can completely change the way you approach your home loan journey.
What Is Lenders Mortgage Insurance (LMI)?
Lenders Mortgage Insurance, often called LMI, is a one-off premium charged when you borrow more than 80% of a property’s value. This means your deposit is less than 20%, and the lender is taking on more risk. Although you pay the cost, LMI protects the lender, not you. If you default on your home loan, the insurer covers the lender’s losses. This is why banks such as ANZ, Westpac, and Commonwealth Bank require it for higher loan-to-value ratios. While it may seem like an extra burden, LMI pays an important role in allowing buyers to enter the market with smaller deposits.
How Much Is Lenders Mortgage Insurance in Australia?
When people ask how much lender mortgage insurance costs, the answer depends on several factors, but generally, LMI sits between 1% and 5% of the loan amount.
For a typical home loan, that can mean a cost ranging from a few thousand dollars to well over $20,000. A $500,000 loan might attract LMI of around $5,000 on the lower end, but it could easily exceed $20,000 if the deposit is very small. Larger loans or higher-risk scenarios can push the cost even higher.
Example: Real LMI Cost Breakdown
- -$500,000 loan with 10% deposit → $8,000 to $10,000+
- -$700,000 property with 5% deposit → $30,000+
- -$600,000 property with 15% deposit → around $5,000
This is why understanding your LMI cost early is so important when planning your home purchase or refinance.
LMI Cost Comparison Table (Real Estimates)
The impact of your deposit size becomes very clear when you look at real numbers.
| Property Price | 5% Deposit | 10% Deposit | 15% Deposit |
| $500,000 | $19,285 | $8,190 | $4,237 |
| $600,000 | $31,008 | $9,828 | $5,100 |
| $700,000 | $36,176 | $12,600 | $5,950 |
| $800,000 | $41,344 | $14,400 | $6,800 |
| $900,000 | $46,512 | $18,711 | $9,104 |
As your deposit increases, the cost of LMI drops significantly. Moving from a 5% deposit to a 15% deposit can reduce your premium by tens of thousands of dollars.
How Is Lenders Mortgage Insurance Calculated?
If you’re wondering how much is lenders mortgage insurance based on, the answer comes down to a few key variables working together. The most important factor is your loan-to-value ratio, or LVR. The higher your LVR, the more risk the lender takes on, and the higher your LMI premium will be. Loan size also plays a role, as larger loans naturally attract higher insurance costs.
The type of property you’re buying, whether you intend to live in it or invest, can influence the premium. Employment type may also affect how lenders assess risk, particularly if your income is variable. On top of that, the insurer used by the lender matters, with providers like Helia commonly underwriting these policies.
How Much Is Lenders Mortgage Insurance on a $500,000 Loan?
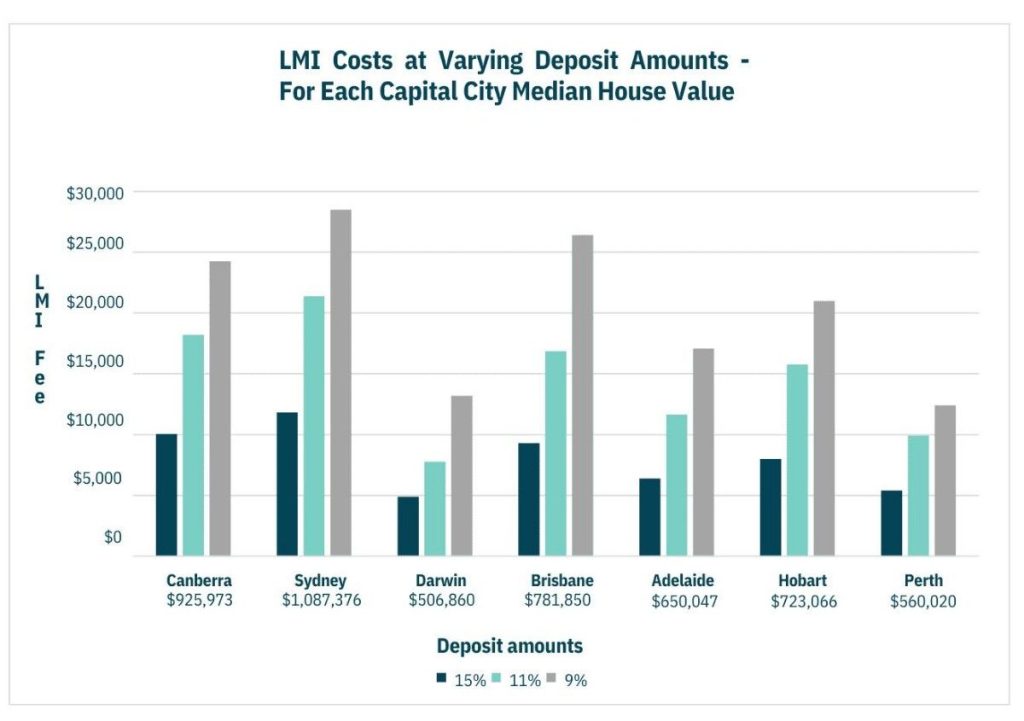
This is one of the most common questions buyers ask, and it highlights how sensitive LMI is to deposit size.
Estimated LMI Costs for $500,000 Loan:
- -5% deposit → $19,000+
- -10% deposit → $8,000 to $10,000+
- -15% deposit → $4,000 to $5,000+
- -20% deposit → $0
Even a small increase in your deposit can lead to significant savings.
Is LMI Paid Upfront or Added to Your Loan?
LMI can be paid upfront as a one-off cost at settlement, or it can be added to your loan balance. Many borrowers choose to capitalise the premium, meaning it becomes part of the mortgage. While this reduces your upfront costs, it also means you will pay interest on the LMI over the life of the loan. In my experience, most first home buyers choose this option simply because it makes entering the market easier.
Is Lenders Mortgage Insurance Expensive?
There’s no denying that LMI can feel expensive. In some cases, it can reach up to 6.5% of the loan amount, particularly when borrowing at very high LVRs. However, the real question is not whether it is expensive, but whether it is worth it. When viewed as a strategic cost rather than just an expense, LMI can actually be a powerful tool.
Is LMI Worth Paying?
From what I’ve seen, LMI can absolutely be worth paying in the right circumstances. If property prices are rising faster than you can save, entering the market earlier may save you far more than the cost of the insurance. For many buyers, especially those paying high rent, LMI provides a pathway to home ownership sooner. It allows you to start building equity immediately rather than waiting years to save a full 20% deposit.
On the other hand, if you are only a few months away from reaching a 20% deposit, it may be smarter to wait and avoid the cost entirely. The value of LMI ultimately depends on timing, market conditions, and your personal financial position.
How to Avoid Lenders Mortgage Insurance with less than 20% deposit
Avoiding LMI is possible, even if you don’t have a full 20% deposit. Here’s where smart borrowers win.
Lender mortgage insurance waiver strategies:
- Guarantor loans (family equity)
- Government schemes like the First Home Guarantee
- Professional waivers (doctors, lawyers, accountants)
- Refinancing with equity
Some lenders (including ANZ and Westpac) offer lender mortgage insurance waiver programs for eligible professionals.
What Is the Difference Between LMI and Loan Protection Insurance?
This is a common area of confusion. Lenders Mortgage Insurance protects the lender, whereas loan protection insurance is designed to protect you.
Loan protection insurance may cover your repayments if you are unable to work due to illness, injury, or other circumstances. LMI, by contrast, provides no direct financial benefit to you.
When Does LMI Apply?
LMI generally applies when your deposit is less than 20% and your loan exceeds 80% of the property’s value. It may also apply when you refinance or increase your loan amount, depending on your updated LVR and risk profile.
Stamp Duty on LMI in Australia By State
Depending on your state, stamp duty may apply to LMI:
- -NSW: No stamp duty
- -VIC: 10%
- -QLD: 9%
- -SA: 11%
- -WA: 10%
- -NT: 10%
Because these charges vary, it’s always a good idea to check official resources like Moneysmart or speak with your lender before finalising your loan.
Lender Mortgage Insurance Calculator
If you want a quick estimate of your LMI cost, using a lender mortgage insurance calculator is the fastest way to get clarity. Tools from lenders such as ANZ LMI calculator and Westpac lenders insurance mortgage calculator can provide tailored estimates based on your loan details. These calculators help you understand how changes in your deposit or loan size can impact your premium.
FAQ: Lenders Mortgage Insurance?
How much is lenders mortgage insurance in NSW?
In most cases, LMI ranges from 1% to 5% of your loan amount. NSW does not apply stamp duty to LMI, which can slightly reduce the overall cost.
What is lender mortgage insurance for first home buyers?
It is a one-off fee that allows first home buyers to purchase property with less than a 20% deposit, making it easier to enter the market sooner.
Can you avoid lender mortgage insurance?
Yes, through options such as guarantor loans, government schemes, or lender-specific waiver programs.
Is LMI refundable?
No, LMI is non-refundable and cannot be transferred to another property or loan.
Should You Pay LMI or Avoid It?
In my view, LMI is not simply a cost to avoid at all costs. It is a financial tool that, when used strategically, can accelerate your entry into the property market and help you build equity sooner. For some buyers, paying LMI is the smartest move they can make. For others, waiting and avoiding it altogether may be the better path. The key is understanding your numbers and making an informed decision.
Ready to See Your Exact Mortgage Cost?
If you’re serious about buying or refinancing, the next step is to stop guessing and start comparing. Head over to RateBuster to compare house loan rates, explore home loan lender options, and use powerful mortgage calculators to estimate your exact costs.