


Guides for Refinances, Home Buyers and Property Investors
There’s a lot to know about home loans.
So we’ve put together some handy guides and tips to help you understand more about home loans.
Ratebuster guides are free to view and download.
What does it mean to refinance a home loan?
What Is Refinancing?
Refinancing a home loan means restructuring your mortgage or switching to a different lender. Homeowners typically refinance a few years into their loan term to unlock equity, reduce fees, or secure a better interest rate.
There are two types of refinancing:
-
External refinancing: Moving to a new lender
-
Internal refinancing: Staying with your current lender but adjusting the loan terms
You might consider refinancing if you started with a high-interest mortgage or plan to switch from owner-occupier to investor. There are many reasons why refinancing could benefit you.
Who Is Refinancing Right Now?
Australia is experiencing historically low interest rates. In 2020, the Reserve Bank of Australia (RBA) dropped the cash rate to nearly zero. As a result, homeowners are saving more than ever. Reduce Home Loans reports customers save an average of $260 monthly—$3,120 annually or $15,600 over five years.
This shift has helped many Australians reduce debt. More borrowers are refinancing to access lower rates, fewer fees, and better loan features. According to Finder, the average refinanced home loan is $440,129. ABS Lending Indicator data from November 2020 shows:
-
Owner-occupiers refinanced $6.58 billion
-
Investors refinanced $4.02 billion
If interest rates continue to fall, this trend will likely grow throughout 2021.
Why Should I Refinance My Home Loan?
Millions of Australians are refinancing—and for good reason. The benefits often outweigh the costs and paperwork. Let’s break down the key advantages:
1. Refinance for a Lower Rate
Securing a lower interest rate is one of the biggest reasons to refinance. Lenders often offer better rates to attract new customers, which means long-term borrowers may be paying more than necessary.
First-home buyers often start with higher rates due to small deposits or lower credit scores. Over time, as equity builds and financial health improves, borrowers gain leverage to negotiate better deals.
💡 Use the to estimate your potential savings.
RATEBUSTER TIP: A lower rate reduces monthly payments and total interest. Switching to fortnightly payments can save even more.
2. Refinance for a New Mortgage Type
Life changes, and so do financial needs. Refinancing lets you adjust your loan’s structure. Common changes include:
-
Switching from owner-occupier to investor loans (or vice versa)
-
Moving from fixed to variable interest rates
-
Changing from interest-only to principal-and-interest repayments
These adjustments can help align your mortgage with your current goals.
3. Refinance to Save Time
Refinancing can shorten your loan term. By choosing a lower interest rate and maintaining your current repayment amount, you’ll pay off more principal each month.
📊 Example: A $450,000 loan at 3% over 30 years has monthly repayments of $1,897. Refinancing to 1.79% (1.88% comparison rate) drops repayments to $1,419. If you keep paying $1,897, you’ll finish the loan 7 years and 4 months early.
4. Refinance to Add Mortgage Features
Many basic loans lack helpful features. Refinancing can add:
-
Offset accounts
-
Redraw facilities
-
Lines of credit
-
Extra repayment options
-
Split accounts
These features offer more control and flexibility, helping you save over time.
5. Refinance to Free Up Equity
Homeowners who’ve paid off a significant portion of their mortgage can access equity. This can fund renovations, weddings, or holidays.
Equity is the portion of your property you own outright. Refinancing allows you to use it as collateral for additional funds—either as a lump sum or line of credit.
RATEBUSTER TIP: Borrowing more increases total interest over the loan’s life—even with a lower rate. Consider long-term costs before tapping into equity.
6. Consolidate Debts
Refinancing can help you merge multiple debts—like personal loans, credit cards, and car loans—into one mortgage payment. Since home loan rates are usually lower, this can reduce monthly expenses.
How to get approved for a home loan.
Lenders have specific eligibility criteria that applicants must meet to approve a home loan and minimize the risk of default. Generally, borrowers must:
a) Be at least 18 years old.
b) Be an Australian resident.
c) Have a stable employment history, preferably with full-time employment for at least 12 months. Self-employed applicants may need to consider low doc loans or seek the help of a specialist broker.
d) Meet the lender’s minimum income requirements.
e) Have a good to excellent credit score.
While the application process can be made easier with online options, there are other important factors that can improve the chances of loan approval. These include paying off outstanding debts, reducing frivolous spending, and avoiding multiple loan applications that can negatively impact credit scores.
It is important to note that lenders will scrutinize an applicant’s spending habits, which can impact their borrowing potential. To increase the likelihood of approval, it is best to minimize entertainment spending for at least three months before applying for a mortgage and avoid multiple applications or rejections.
What are the costs of refinancing a home loan?

Refinancing your home loan is not free, and it is crucial to weigh the costs, risks, and potential downsides of any financial product before making a final decision. These considerations may include:
1) Switching fees
When you initially applied for your home loan, you likely paid several upfront fees like application and valuation fees. However, when you decide to refinance your mortgage, you may need to pay new upfront fees to the new lender.
Additionally, if you’re leaving a fixed rate loan early, you may have to pay a break fee and a discharge fee to your existing lender. It’s also important to keep in mind any government charges like mortgage registration costs. Whenever a mortgage is established or discharged against a property, a mortgage registration fee must be paid.
2) Extending your mortgage term
When homeowners refinance their mortgage, some may fall into a risky trap of extending their mortgage term. Generally, mortgage terms range from 25 to 30 years, and if you have already paid off, say, ten years of your 30-year home loan, it would not be wise to refinance to a new 30-year home loan. By doing so, you will end up paying tens of thousands of dollars more in interest over time.
3) Time, effort and paperwork
According to a report by RateCity, 40% of people who refinance their home loans view the time and effort required as a major obstacle. Refinancing requires a significant amount of effort from borrowers, including reapplying for the loan, getting their property valued, and providing personal documents like bank statements and proof of identification.
While it’s important to consider the costs involved, it’s essential to note that the potential savings in terms of time and money may outweigh the initial expenses and stress.
RATEBUSTER TIP: Consider refinancing as it may pay off faster than you anticipate. For instance, if you’re refinancing expenses amount to $1,500, and your yearly interest savings are $3,120 (typical for our customers), you could cover your refinancing costs in under 6 months.
When shouldn’t I refinance my home loan?

When Refinancing May Not Be the Right Move
Refinancing can be an appealing way to reduce mortgage costs or access better loan features. However, it’s not always the right choice. If you’re unsure whether to refinance or stick with your current loan, consider the following factors carefully.
1. You Haven’t Built Up Enough Equity
Not all homeowners will qualify for better rates through refinancing. Lenders assess your Loan-to-Value Ratio (LVR) to decide if you’re eligible for lower interest rates—or for approval at all.
💡 RATEBUSTER TIP:
Aim to keep your LVR at or below 80%. A higher LVR may mean less competitive loan options and a greater chance of rejection.
2. You’re Near the End of Your Loan Term
Refinancing often resets your loan term to 25 or 30 years. If you’ve only got a few years left, this could cost you tens of thousands more in interest over the life of the loan—even if your new rate is lower.
3. You’ll Still Owe Lender’s Mortgage Insurance (LMI)
If your equity is below 20%, you’ll likely need to pay LMI again when refinancing. This one-time premium can cost several thousand dollars, making refinancing less beneficial—even if it offers a lower rate.
4. You’re on a Fixed Loan
Breaking a fixed-rate loan can trigger a break fee, which lenders charge to offset their losses. These fees can range from a few hundred to over a thousand dollars, depending on your contract and remaining term.
💡 RATEBUSTER TIP:
Some lenders offer cashback incentives to help cover break fees or other refinancing costs. Always ask your broker or lender about available offers.
How Long Does Refinancing Take?
On average, refinancing takes 2–4 weeks, depending on your paperwork, property valuation, and lender responsiveness. This timeline can discourage some borrowers from pursuing it.
However, open banking is starting to change that. With this system, banks can securely access your financial data (with your consent), making it easier to verify income, credit, and expenses.
As more lenders adopt open banking, refinancing may become as simple as a few clicks—no more chasing down months of statements or ID documents.
For now, though, expect the standard 2–4 week timeline from application to settlement.


Am I eligible to refinance my mortgage?

It is important to consider the eligibility criteria of the lender and home loan before applying for a mortgage refinance, as not all homeowners may be in an ideal position to do so. These criteria can typically be found in the terms and conditions, with additional information on fees and costs available in the product disclosure statement.
While meeting the most basic eligibility criteria that were required for the original home loan is a given, there are other factors that may affect your approval for mortgage refinancing. To ensure your eligibility, it is recommended that you check for four key areas:
a) A good to excellent credit score
b) Regular payments towards any debts (car loan, personal loan, credit cards, HECS/HELP debt)
c) At least 20% equity paid into your mortgage
d) A stable employment
Note: Although lenders may prefer borrowers with full-time employment, those who are part-time, casually employed, or self-employed may still be eligible for a new mortgage through a low-doc home loan.
If you do not meet three or more of these eligibility criteria, it may be wise to consider improving your personal finances and/or credit history before applying for a new home loan.
What are some refinancing traps to avoid?
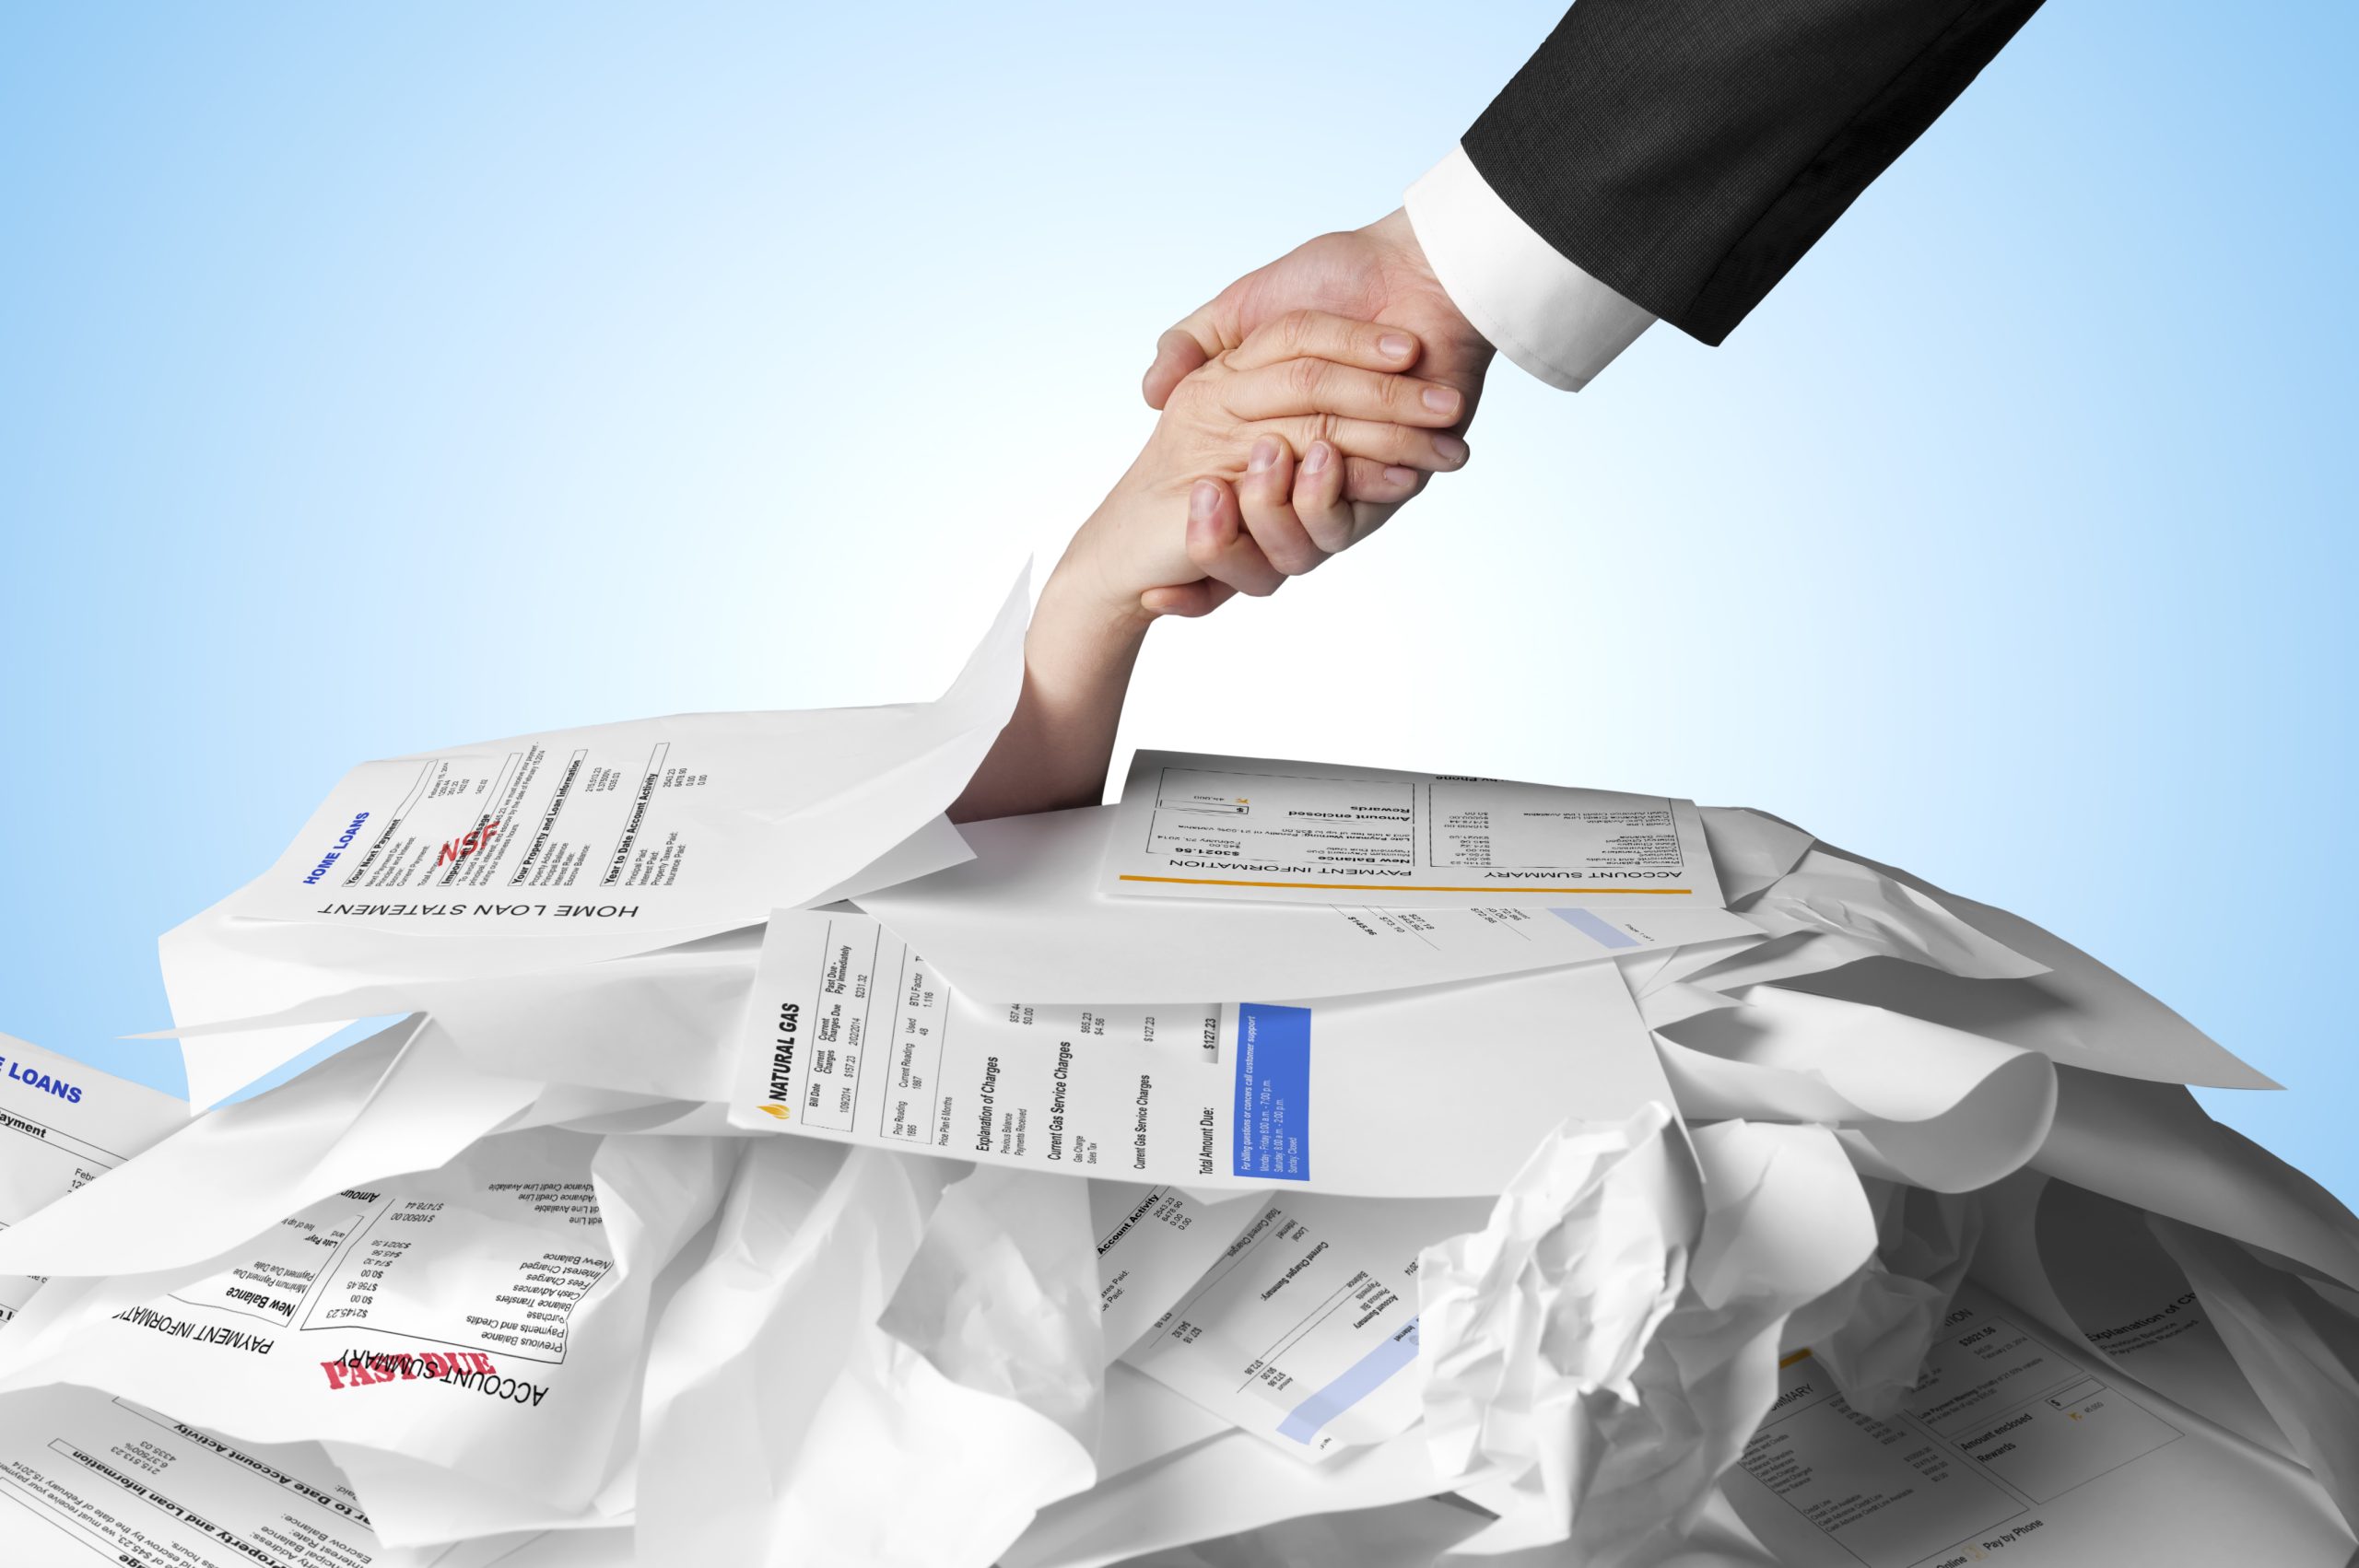
As a homeowner, you should be cautious of the following common refinancing pitfalls to avoid falling into them:
a) Refinancing to a longer loan term
One error that many homeowners commit is refinancing their mortgage for a longer term than their current one.This happens when a borrower, who has already completed, let’s say, 10 years of a 30-year mortgage, fails to discuss with the new lender about maintaining the same remaining term. As a result, they may find themselves starting a new 30-year loan, and ultimately taking 40 years to fully repay their mortgage.
b) Taking on more debt
Once you’ve paid off a portion of your home loan over a few years, you might discover that you can borrow a larger sum of money when it’s time to refinance. You might even aim to access this equity through refinancing to fund home improvements or cover the costs of a wedding.
Nevertheless, some borrowers might not have a specific objective in mind and may end up borrowing more than they can manage. By increasing the balance of your mortgage, you’ll ultimately pay more over the duration of the loan due to interest repayments.
c) Neglecting to factor in fees
When refinancing to lock in a lower interest rate, it’s important to consider more than just the interest rate itself. Ongoing fees associated with the loan can significantly impact your new repayments. To ensure you are fully informed, carefully review the product disclosure statement for any loan you are interested in and pay attention to ongoing fees, such as annual fees, which may vary depending on the lender and cost hundreds of dollars.
If your current lender charges a higher rate but fewer fees, it’s crucial to do some mortgage calculations to determine if refinancing will still be financially beneficial, taking into account any potential fees associated with the new loan. Ultimately, to make the most informed decision, it’s important to consider both the interest rate and the associated fees when refinancing.
RATEBUSTER TIP: As you shop around for a home loan refinancing option, be sure to look out for potential savings such as zero ongoing annual fees, which is a benefit offered to our customers.
d) Consolidating smaller debts
One option for homeowners looking to pay off smaller debts like credit card or car loan is refinancing. By refinancing and borrowing a greater amount, homeowners can consolidate their debts into their mortgage.
It’s worth noting, however, that although home loan interest rates are typically lower than those of personal loans or credit cards, using a mortgage to pay off these debts means extending them into a 20 to 30-year loan. While a 3-year car loan may have a higher interest rate, the amount of interest paid over 3 years is usually significantly less than what would be paid over 30 years with a mortgage.
e) Honeymoon rates
It’s important to be aware that when it comes to home loans, it’s not just about the fees and higher debt you should be concerned with. Many home loan lenders use competitive, short-term interest rates to lure in new customers. These rates are often referred to as introductory or “honeymoon” rates.
While these rates may provide temporary repayment relief (typically lasting 12 months to a few years), it’s important to note that the interest rate will eventually revert to a higher standard variable rate. Before you consider applying for a loan with a competitive honeymoon rate, make sure you are aware of the exact interest rate it will revert to once the honeymoon period is over. Additionally, be sure to assess whether you can afford this rate without falling into mortgage stress.
What documents do you need for refinancing?
If you’ve confirmed your eligibility to refinance and established your refinancing objectives, you may be interested in knowing what’s involved in the refinancing process.
When refinancing, the lender will generally require the same documents you provided during your initial home loan application. The documents requested usually include:
1) Proof of personal identification (such as a driver’s license, passport, or birth certificate)
2) Evidence of income (such as three months of bank statements, payslips, and tax returns)
3) Details of any existing loans (such as home loan statements, credit card statements, and balances of other debts, including HECS and personal loans)
4) Records of any other assets you may have (such as shares or investment properties)
5) A copy of your current rates notice and proof of payment.
Collecting these documents may take some time, so it’s a good idea to prepare them ahead of time when applying to refinance a loan. This can help speed up the refinancing process, enabling you to apply in a matter of minutes.
Once you’ve submitted your application, your new lender may conditionally approve it. At this point, a representative will come to value your property, giving you the perfect opportunity to ensure any repairs or renovations you’ve been considering are completed.
Finally, your new lender will provide you with your new mortgage contract, granting their full approval. They will then pay out your previous mortgage, and you will have officially completed the refinancing process.
Refinancing FAQs
When should I refinance your mortgage?
Refinancing your mortgage may be a suitable option if you are eligible and looking to accomplish several financial goals such as reducing mortgage repayments, changing the type of loan, unlocking equity, shortening the loan term, adding mortgage features, or consolidating debts.
Is now a good time to refinance?
The ideal timing for mortgage refinancing varies according to the individual’s financial circumstances and the objectives behind the refinance. Currently, Australia is undergoing an unprecedented era of low-interest rates, prompting a surge in homeowners seeking to refinance their mortgages. It’s advisable to capitalize on any superior offerings that may be available in the market.
Can I refinance if I just refinanced?
You may be able to refinance immediately after refinancing, but it’s worth keeping in mind the costs involved may outweigh the benefits of switching home loans. You will also need three months of home loan statements.
Can I refinance if I have other products bundled with my home loan?
It is possible to refinance a packaged home loan, but it may require extra documentation to separate all your financial products. Certain lenders may provide assistance with this process to help you meet the requirements.
Can I change jobs while I am refinancing my home loan?
Home loan lenders typically view applicants who have held steady employment with the same company for 6-12 months more positively, as it suggests a greater level of financial stability.
Who has the best home loan?
The ideal home loan for each individual can vary significantly depending on their unique financial situation and borrowing needs. Therefore, it is recommended to conduct thorough research and compare various options before deciding to refinance.
How much equity do I need to refinance?
Borrowers who have paid down at least 20 percent of their mortgage are viewed more positively by home loan lenders. Additionally, this enables them to avoid expensive lenders mortgage insurance.
Can I refinance an investment loan to an owner-occupier loan?
It is possible to obtain financing as an investor, but it’s important to note that lenders often charge higher interest rates to investors compared to owner-occupiers. This is because investors are perceived to take on more risk with property investments.
What is mortgage stress?
A typical definition of mortgage stress is when an individual allocates more than 30 percent of their income towards their mortgage payments.
What is the difference between an offset account and redraw facility?
Two distinct features of home loans are offset accounts and redraw facilities. Offset accounts involve linking a bank or savings account to a mortgage, with any deposited funds being used to “offset” or decrease mortgage repayments. For example, if you have a $500k loan and $50k in an offset account, your mortgage repayments would be calculated based on a reduced loan amount of $450k. Redraw facilities enable borrowers to access any extra repayments made towards their loan.
RATEBUSTER TIP: If you transfer your extra savings to your redraw facility, they function similarly to being in your offset account, where they offset the value of your home loan. However, the advantage of using a redraw facility is that you can withdraw the funds as needed.
Is it safe to get an online home loan?
It is possible to safely apply for a home loan through an online lender. Online lenders have fewer overhead costs compared to traditional brick-and-mortar banks, which can translate into lower interest rates and fees for their customers. However, it’s important to thoroughly research the lender before submitting an application.
Is it safe to get a home loan outside the big four banks?
It is indeed secure to seek a home loan from financial institutions outside of the prominent four banks. In fact, in numerous cases, it can prove to be a more economical option.
Can I consolidate my credit card and other debts with my home loan?
It is possible to combine your debts into your home loan during the process of refinancing.
How long does refinancing take?
In general, the process of refinancing can span from 2 to 4 weeks, which may vary depending on various factors such as the duration taken to collect and furnish personal documents, valuation, and other related aspects.
How much equity is needed to refinance?
To qualify for refinancing, the required equity amount is determined by the home loan lender’s eligibility criteria. It’s advisable to aim for a minimum of 20 percent equity deposited in your loan, according to professionals, to increase your likelihood of being approved.
Does refinancing affect my credit score?
Refinancing has the potential to affect your credit score, as any application for a home loan typically results in a hard inquiry on your credit report. Your credit score may be adversely affected by factors such as making several loan applications or having your loan application rejected. Additionally, closing a bundled credit card with your previous home loan may also contribute to a decrease in your score. On the other hand, consistent repayment of your new mortgage may be interpreted as a favourable action and increase your score.
Guides for Refinances, Home Buyers and Property Investors
There’s a lot to know about home loans.
So we’ve put together some handy guides and tips to help you understand more about home loans.
Ratebuster guides are free to view and download.
